
If you’re evaluating St Albans as an investment market, you’ll find a premium location supported by constrained supply, commuter demand and high-performing school catchments. Price resilience has historically outpaced many surrounding areas, while varied housing stock creates different routes to rental income and capital growth. However, returns can vary sharply by neighbourhood, property type and entry price—making local analysis the deciding factor.
Key Takeaways
- St Albans benefits from strong London commuter demand, fast Thameslink access, high household incomes, and appeal to professionals, families, and downsizers.
- Limited developable land, planning constraints, and low listing volumes underpin price resilience and reduce oversupply risk in premium neighbourhoods.
- Family homes near reputable schools and green spaces typically offer durable tenant demand, longer tenancies, and stronger rental resilience.
- Apartments near City station, Central St Albans, Fleetville, and Hatfield Road attract professionals seeking efficient layouts and convenient transport connections.
- Investors should assess net yields after financing, maintenance, service charges, voids, and legal considerations, rather than relying on headline rents.
Is St Albans a Good Property Investment?
St Albans remains a strong property investment market because it combines London commuter demand, limited housing supply and consistently high buyer purchasing power. You can target a deep tenant pool of professionals and families seeking fast rail access, strong schools and established amenities.
Market Trends indicate sustained demand for well-located period homes, modern apartments and family-sized properties near stations and city-centre services.
Your Investment Strategies should prioritise assets with broad renter appeal, efficient layouts and manageable running costs. Compare achievable rents against purchase prices, mortgage rates, service charges and anticipated maintenance before committing.
You’ll find that proximity to Thameslink connections, employment centres and reputable schools can support occupancy levels. Focus on realistic cash-flow scenarios rather than headline rental estimates, and allow for void periods, compliance costs and refurbishment budgets.
This approach helps you assess whether returns meet your risk and time horizon.
Why St Albans Property Prices Stay Resilient
The same fundamentals that support rental demand also underpin St Albans’ price resilience: constrained supply, high household incomes and reliable London connectivity.
You’re investing in a market where buyer demand draws from commuters, families and downsizers, reducing reliance on one purchaser group. This Market diversification helps values absorb changes in mortgage rates or wider economic confidence more effectively than less affluent locations.
Recent pricing patterns show that premium, well-connected Hertfordshire markets typically recover quickly after periods of uncertainty, particularly where schools, amenities and rail access remain strong.
You can also use Rental yield strategies to support holding power: dependable tenant demand helps offset financing costs while you wait for capital values to strengthen.
For investors, resilience stems from demand quality, household purchasing capacity and the area’s enduring appeal to London-linked buyers.
Limited Supply and Long-Term Price Stability
Limited developable land, planning constraints and strong owner-occupier retention restrict the number of homes entering St Albans’ market, even as demand remains broad. For you, this supply-demand imbalance provides an important buffer against cyclical weakness.
When listings stay scarce, buyers compete for well-positioned homes, supporting achieved prices even when transaction volumes soften.
Market liquidity can tighten during higher-rate periods, yet constrained stock means sellers aren’t forced to discount heavily. Instead, fewer completed sales often reveal selective buyer behaviour rather than widespread value erosion.
You should consequently assess pricing through longer rolling periods, not short-term monthly movements.
Price fluctuations still occur between neighbourhoods, property types and condition levels. However, limited new supply reduces the risk of sustained oversupply, helping St Albans maintain steadier long-term price performance than markets with larger development pipelines.
Commuter Links That Support St Albans Values
Although hybrid working has reduced daily commuting for some households, St Albans’ fast rail access to central London continues to underpin buyer demand. You can reach St Pancras International in roughly 20 minutes from St Albans City, giving the town a measurable advantage over locations with longer, less predictable journeys.
This commuter connectivity broadens the buyer pool, attracting professionals who want flexible office access without sacrificing space or amenities.
Transportation infrastructure also supports resilience beyond rail. Direct road links via the M1, M25 and A1(M), alongside proximity to Luton Airport, strengthen St Albans’ appeal for regional and international travel.
As employers maintain hybrid policies rather than fully remote models, you’re likely to see convenience retain a price premium. Efficient access reduces commute friction, helping premium homes hold demand through changing market cycles.
How School Catchments Protect Property Demand
Strong school catchments create a durable layer of demand in St Albans, where family buyers often prioritise admission prospects alongside commute times and home size.
When you assess local pricing, homes within sought-after primary and secondary catchment boundaries typically attract a wider buyer pool and can sell more consistently through softer market periods.
School catchments reduce substitutability: buyers may compromise on layout, condition or garden size to secure an address linked to preferred schools.
This concentrates property demand in specific streets, creating sharper price differences between nearby locations.
You should track admissions criteria, oversubscription patterns and boundary changes, as these can affect buyer behaviour quickly.
St Albans’ established education offer supports repeat family demand, helping well-positioned homes retain liquidity.
For investors, proximity to respected schools strengthens the long-term case for selective purchases.
Rental Demand in the St Albans Market
School catchments support owner-occupier demand, while St Albans’ rental market draws on a broader mix of London commuters, relocating professionals, families and local employees. For you as an investor, this diversified tenant base can reduce reliance on any single demand driver.
Fast rail connections to central London, a limited supply of well-presented homes and strong local employment underpin competition for rentals.
Demand is typically strongest for efficient one- and two-bedroom Luxury apartments near transport, alongside family houses that offer space and practical access to schools and amenities.
Student housing represents a smaller, more specialised segment than in major university cities, so you shouldn’t treat it as the market’s core yield engine. Instead, assess achieved rents, void periods and tenant affordability against asking prices.
Properties with modern specifications, energy efficiency and flexible layouts should retain wider appeal as renter expectations rise.
St Albans Areas for Growth and Rental Demand
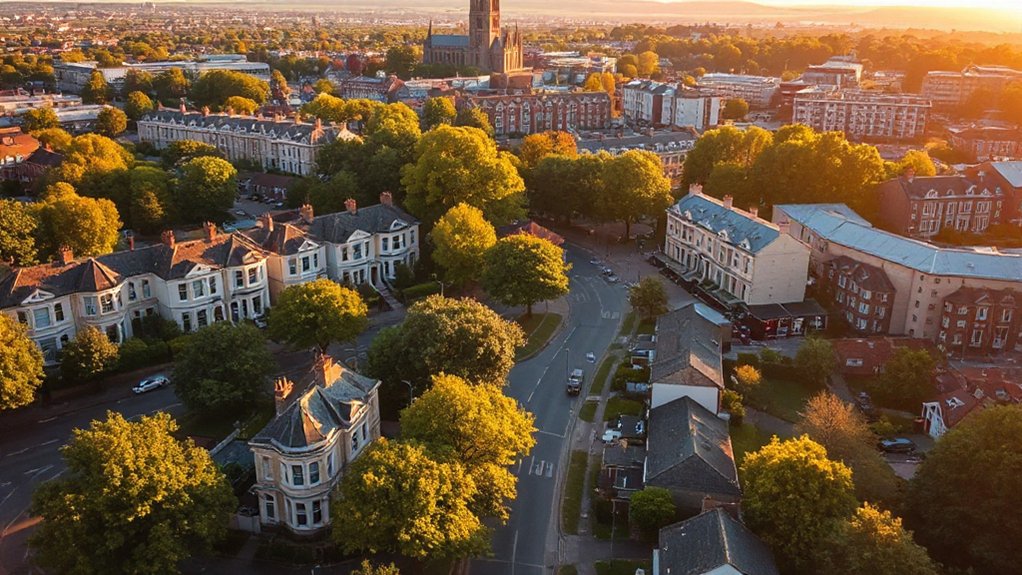
Growth and rental demand vary sharply across St Albans, so you should assess each micro-location by its transport access, housing mix and tenant profile rather than rely on town-wide averages.
Central St Albans and the City station catchment typically command resilient demand from London commuters, supported by rapid rail links, established local amenities and constrained supply.
Areas near St Albans Abbey appeal to tenants prioritising character, walkability and access to the city centre.
You should also track Fleetville and Hatfield Road, where connectivity, regeneration activity and comparatively accessible price points can widen the tenant pool.
Marshalswick and St Stephen’s attract family renters seeking schools, green space and neighborhood safety, although affordability can limit yields.
Compare achieved rents, listing durations and vacancy levels quarterly. This reveals whether price growth reflects genuine rental depth or short-term buyer sentiment.
Best St Albans Property Types for Investors
Once you’ve identified the St Albans locations with sustained tenant demand, match the property type to the dominant renter profile and local price-to-rent ratio. You’ll typically find that well-presented one- and two-bedroom Luxury apartments appeal to professional tenants seeking station access, low maintenance, and modern specifications. These units can support efficient lettings where convenience drives decision-making.
Family-sized Victorian and Edwardian houses target longer-term occupiers, particularly near established schools and green space. Although acquisition prices are higher, larger homes may deliver steadier tenancy durations and stronger rental resilience.
Historic cottages attract tenants prioritising character and central lifestyle access, supporting premium positioning when interiors meet contemporary expectations.
Compare each format using achievable rent per square foot, likely void periods, refurbishment requirements, and tenant turnover. Your best choice isn’t simply the highest-yielding asset; it’s the property whose demand profile aligns with your investment horizon and income objectives.
Key Risks in St Albans Property Investment
Even in a high-demand market, St Albans investment returns can weaken if you underestimate entry pricing, mortgage costs, and the gap between headline rents and net income. Premium purchase values can compress yields, while rate changes quickly alter monthly cash flow and affordability tests.
You’ll also face market volatility: slower price growth, reduced buyer activity, or rising stock levels can lengthen resale periods and limit capital gains.
Operating costs matter. Maintenance on older homes, service charges on leaseholds, insurance, void periods, and letting fees can erode projected returns.
Legal complexities can add delays and expense, particularly around lease terms, planning restrictions, conservation areas, title issues, and landlord compliance.
You should also account for EPC requirements and changing rental regulations, which may require capital upgrades before you can let or refinance efficiently.
Building Your St Albans Investment Strategy
You should define clear return, risk, and holding-period objectives before comparing St Albans opportunities.
Use price growth, rental demand, vacancy rates, and planned infrastructure to identify high-growth areas.
Balance stronger rental yield against long-term capital appreciation so your portfolio matches current market trends and your financial targets.
Defining Investment Objectives
A clear investment objective gives your St Albans strategy a measurable framework, linking your time horizon, risk tolerance and target returns to the area’s property trends. Define whether you prioritise rental income, capital preservation, long-term appreciation, or a blended outcome.
Your Investment timeline should guide financing choices, expected holding periods and exit assumptions; shorter horizons require stronger liquidity buffers, while longer horizons can absorb cyclical price movements.
Set return targets against realistic metrics, including net yield, annual costs, borrowing rates and projected capital growth. Stress-test your assumptions for vacancy, maintenance and rate changes to identify downside exposure.
Market diversification can reduce concentration risk by balancing property types, tenant profiles or investment vehicles. Review objectives annually, comparing actual performance with your target benchmarks. If conditions or personal circumstances change, adjust your allocation and financing strategy rather than letting outdated goals dictate decisions.
Selecting High-Growth Areas
Where growth concentrates in St Albans depends on measurable demand drivers rather than postcode reputation alone. You should track transaction volumes, days on market, price changes, planning applications, and buyer enquiry patterns at neighbourhood level.
Areas near rail links, highly rated schools, parks, and expanding retail corridors often show deeper demand resilience. Analyse Neighborhood demographics closely: rising professional households, family formation, and downsizer activity can signal sustained competition for specific property types.
You’ll also want to map upcoming infrastructure and commercial investment against current supply constraints. New cafés, premium fitness spaces, independent dining, and other Luxury amenities can strengthen an area’s appeal when they align with resident spending capacity.
Compare micro-markets across St Albans quarterly, identifying locations where demand is accelerating before pricing fully reflects the shift. Use evidence, not assumptions, to prioritise areas with durable momentum.
Balancing Yield And Appreciation
Balancing rental yield against capital appreciation requires you to model each St Albans opportunity on both current income and likely long-term value growth. Compare gross and net yields after management, maintenance, financing, and void-period assumptions.
Then test appreciation potential against local supply, school catchments, rail connectivity, and buyer demand trends. Higher-yield properties may improve cash flow, while premium family homes can offer stronger resilience and longer-term price momentum.
You shouldn’t rely on a single property profile. Market diversification across central, suburban, and regeneration-linked locations can reduce exposure to one demand cycle.
Investment diversification also lets you combine income-focused flats with growth-led houses. Stress-test rent increases, interest-rate changes, and slower sale conditions.
Your target should be a portfolio whose income supports holding costs while its assets retain credible potential for inflation-beating appreciation over time.
Frequently Asked Questions
What Are the Stamp Duty Costs for St Albans Investment Properties?
Stamp duty on St Albans investment properties follows England’s additional-property rates: you’ll pay 5% up to £125,000, rising through bands to 17%. Your property tax liability depends on price, reliefs, and ownership structure.
How Does St Albans Compare With Nearby Hertfordshire Investment Towns?
St Albans typically commands higher prices than nearby Hertfordshire towns, but you gain resilient rental demand, stronger commuter appeal, and premium tenant profiles. Market trends favour steady capital preservation, while Watford and Hemel Hempstead may offer higher yields.
What Landlord Licensing Requirements Apply in St Albans?
You must meet national landlord regulations, including safety certificates, deposit protection, and right-to-rent checks. St Albans may require selective or additional HMO licences in designated areas, so verify licensing compliance with the council before letting.
Can Overseas Buyers Invest in St Albans Property?
Yes, you can invest in St Albans property; it’s not a closed door. Overseas investor opportunities remain strong, though International property regulations, tax rules, financing availability, and transaction costs can affect your projected returns.
What Tax Relief Is Available for Buy-To-Let Investors?
You can claim Tax reliefs on mortgage-interest costs at the basic rate, allowable expenses, repairs, and capital allowances where eligible. Investment incentives include pension planning and CGT allowances, though thresholds and rules change frequently.

Leave a Reply